Oil Is Hot, Chips Are Wobbling, and Banks Must Show Their Work
October 14th, 2026 · Daily Wall Street Alerts Editor · 5 minute read
Monday’s market offered the sort of mixed scorecard Wall Street likes to call “resilient.” The Dow rose 0.4%, while the S&P 500 slipped 0.1% and the Nasdaq fell 0.4%. Energy shares rallied as chips sagged. More than four in ten S&P 500 stocks are down this year even as the index is up about 14%, with gains concentrated in a small group of chipmakers and other AI-linked giants.
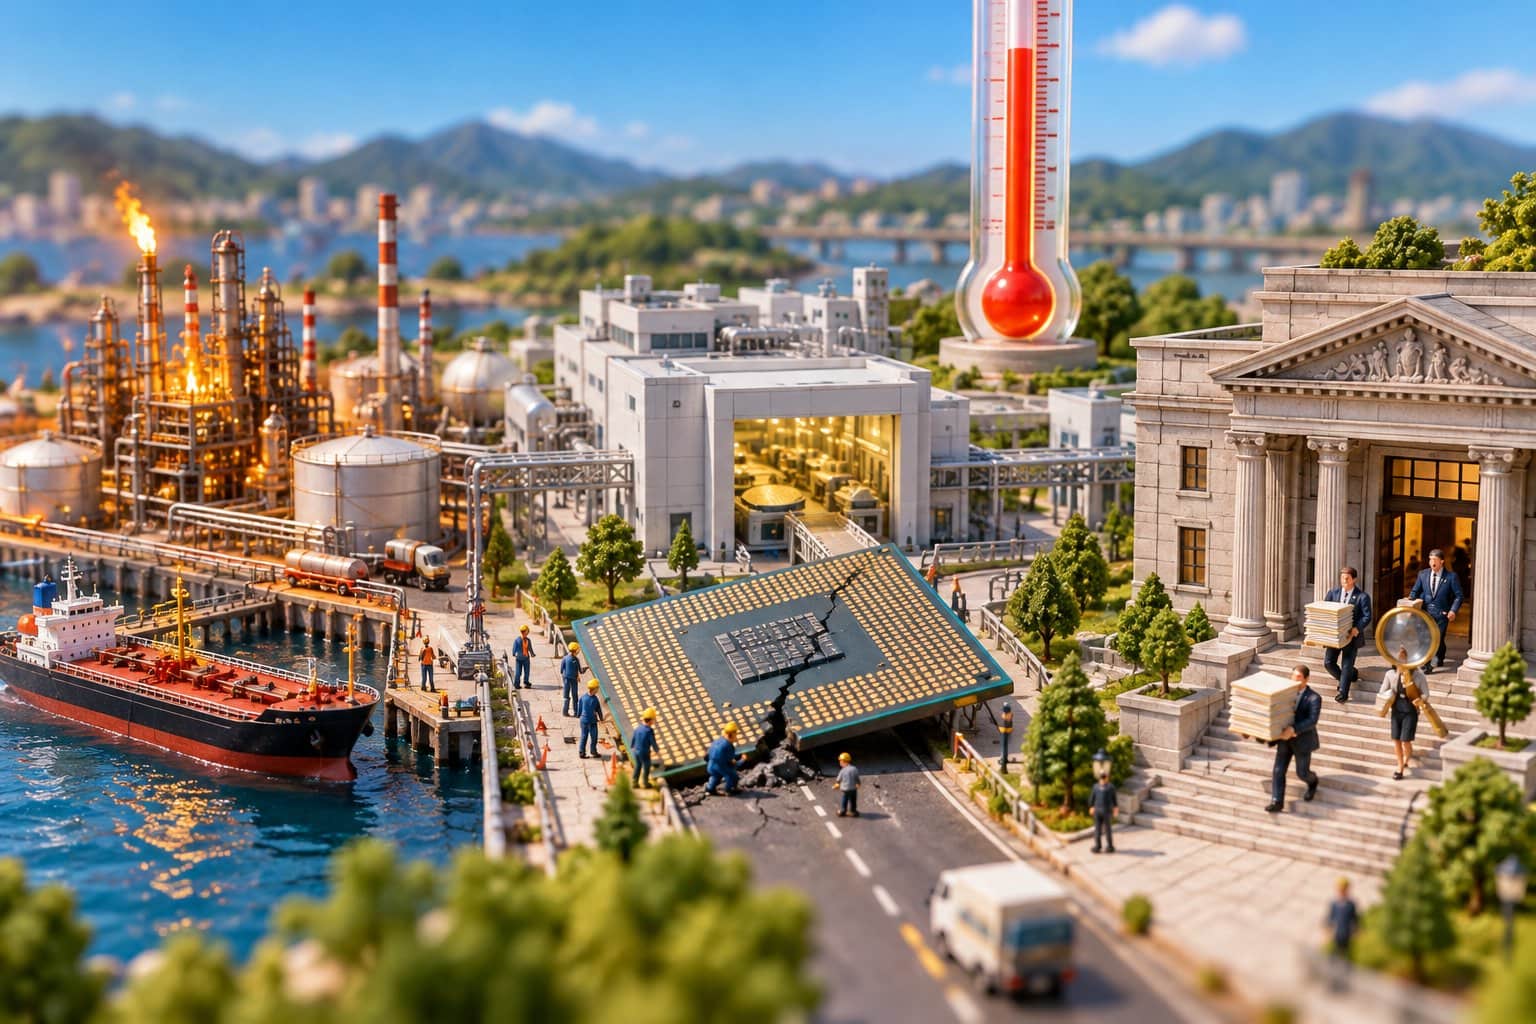
That is the tension we’re watching: concentrated optimism meets expensive realities. Oil can feed inflation; new competition can challenge chip margins; and banks must show that their profits can keep up with the market’s expectations. Here are three sector stories worth following—not because a headline is a trade, but because each has a clear test ahead.
Energy: A geopolitical premium is not a business model
Energy led the S&P 500 sectors Monday, up about 1.4%, while the State Street Energy Select Sector SPDR ETF (XLE) touched a new intraday high. Brent crude settled at $106.65 a barrel.
The market was repricing supply risk after Houthi attacks on Saudi Arabia and reports of attacks on tankers near the Strait of Hormuz, even as hopes for additional Russian diesel supply offered a counterweight.
Higher realized prices can help producers, and XLE offers a broad sector lens; Exxon Mobil (XOM) is another representative name to study. But separate a durable cash-generation story from a temporary risk premium: if shipping disruptions ease, crude could surrender some of its geopolitical markup, while sustained high prices may squeeze consumers and raise costs elsewhere.
That inflation channel matters this week. September’s CPI is scheduled for Wednesday; analysts surveyed by Schwab expected headline inflation to rise 0.6% month over month, versus 0.2% for core CPI excluding food and energy. Those are forecasts, not results, but the gap makes energy prices impossible to ignore when reading the inflation report.
For XLE or XOM, ask how much earnings depend on today’s oil price, what production costs and capital plans look like, and whether the rally reflects supply risk more than better operations.
Semiconductors: AI demand is real; pricing power is still contested
The semiconductor and optical-hardware complex got a blunt reminder that “AI exposure” is not a protective moat. Monday, the iShares Semiconductor ETF (SOXX) fell 2.6% and the Roundhill Memory ETF (DRAM) lost 4.3%; Lumentum, Ciena, Coherent, and Corning fell roughly 6% to 9.5%.
The pressure sharpened Tuesday morning after Chinese memory-chip maker CXMT said it had made progress on a denser memory design and planned a server product before year-end. Bloomberg said the claim was not independently substantiated; Reuters reported that the news stoked competition concerns. A company announcement is not proof the product will meet performance, yield, or customer-qualification hurdles—but if supply expands, investors should ask who keeps the margins.
This is not an obituary for AI infrastructure. It is a reminder that strong demand does not guarantee attractive returns for every supplier. Investors should ask whether growth is translating into pricing power and returns on the enormous capital being committed.
For research, SOXX offers a diversified sector view, while Micron Technology (MU) is a direct way to study memory economics. Track product mix, customer concentration, competitive capacity, and whether earnings expectations are outpacing delivery. A new competitor does not instantly displace incumbents, but dismissing competition because the AI story is popular risks paying peak multiples for yesterday’s advantage.
Financials: The earnings bar is lower, not optional
The third-quarter reporting calendar is putting banks in the spotlight. JPMorgan Chase, Goldman Sachs, Wells Fargo, and Citigroup are on Tuesday’s slate; Bank of America, Morgan Stanley, BlackRock, and State Street are scheduled for Wednesday. September CPI is due Wednesday, too.
The setup is less flattering than the index’s headline earnings story. Schwab, citing FactSet, put expected year-over-year earnings growth for the S&P 500 financials sector at 3.3%, against 7.4% revenue growth. FactSet’s October 9 estimate for the broader S&P 500 was 29.6% earnings growth, with only 19 companies having reported. These are estimates, not results, and the dates differ; still, “banks are reporting” is a catalyst, not automatically a bullish thesis.
JPMorgan (JPM) and XLF, the Financial Select Sector SPDR ETF, are research starting points. Look beyond a one-cent earnings beat: watch net interest income and guidance, loan-loss provisions, credit stress, loan demand, and trading or investment-banking revenue.
If management teams sound cautious about borrowers or future net interest income, a headline beat may not settle the argument. Listen for specifics, not polished adjectives.
Wrap-up
Energy, semiconductors, and banks tell one story: investors are being asked to pay now for uncertain future conditions. Will the oil premium last? Can AI demand coexist with chip competition and margins? Can bank earnings justify confidence in a market where gains remain concentrated?
We would watch Wednesday’s CPI and the earnings details—not just the first percentage move after the release. Wall Street can turn a hot sector into a tidy story in a hurry. Independent investors still have to check the cash flows, the competition, and the assumptions hiding in the price.
— The Daily Wall Street Alerts Team
This newsletter is for informational purposes only and does not constitute investment advice. Always conduct your own due diligence before making any investment decisions.